Real Estate: How to Invest in Real Estate
Introduction to Real Estate: How to Invest in Real Estate, Develop Property, and Build a Profitable Property Business
A client called me last year, genuinely upset. He had bought a plot in an “up and coming” area on the strength of a WhatsApp flyer, no survey, no title verification, no idea what the land was zoned for. Two years later, the “estate” still had no access road, no drainage, and no C of O in sight. He wasn’t a foolish man. He was a busy one, and busy people get sold dreams instead of due diligence.
I’m writing this because I’ve sat on both sides of that conversation more times than I can count as the Town Planner explaining why a plot can’t be developed the way the seller promised, and as the designer trying to make a bad piece of land work for a client who already paid for it. Real estate rewards patience and process. It punishes shortcuts, and it punishes them slowly, which is what makes them so easy to fall into.
This is the long version of everything I’d tell you if we sat down together whether you’re buying your first plot, trying to understand what a “developer” actually does, deciding between residential and commercial property, or trying to figure out if rental income can actually replace your salary one day. Grab a coffee. This one is thorough on purpose.
Real Estate Investment and Investing
Real estate investment, at its core, is the deliberate use of money to acquire property land, buildings, or interests in either with the expectation that it will produce income, appreciate in value, or both. That sounds simple. What makes it complicated is that “real estate” isn’t one asset class; it behaves completely differently depending on what you buy, where you buy it, and how you finance it.
Why Real Estate Behaves Differently From Other Investments
Unlike stocks or a savings account, real estate is illiquid you can’t sell a house in an afternoon the way you can sell shares. It’s also leveraged more easily than most assets; you can control a property worth many times your cash outlay through a mortgage or installment arrangement, which magnifies both gains and losses. And it’s local a national economic boom doesn’t automatically lift every neighbourhood equally; a specific road project, a new school, or a state government’s infrastructure plan can move one street’s value while leaving the next one flat.
The Three Ways Real Estate Actually Makes Money
Almost every real estate return, anywhere in the world, comes down to a combination of three things:
Appreciation the property becomes worth more over time, usually driven by location improvement, infrastructure, scarcity, or inflation
Income rent, lease payments, or other cash flow the property generates while you hold it
Value-add you actively increase the property’s worth through development, renovation, subdivision, or improved use, rather than waiting passively for the market to do it
Most inexperienced investors chase appreciation alone, because it’s the story everyone tells at parties. The investors who actually build wealth in real estate usually combine all three buying for income, in a location likely to appreciate, while looking for a value-add angle the market hasn’t priced in yet.
The Risks Nobody Puts in the Brochure
Real estate risk isn’t abstract it’s specific and knowable if you ask the right questions. Title risk (does the seller actually have clear, transferable ownership?), liquidity risk (can you exit if you need cash urgently?), concentration risk (is your entire net worth tied up in one property in one location?), and regulatory risk (can the government’s planning or land-use decisions change what you’re allowed to do with the property?) are the four that catch the most investors off guard, and every one of them is checkable before you commit money.
Before you ask “will this property appreciate,” ask “can I actually exit this if I need to in two years.” Illiquidity is the risk most new investors underestimate the most, because it’s invisible until the exact moment you need it not to be.
Real Estate Investing for Beginners
If you’re starting from zero, here’s the honest sequence not the version that sells a course, the version that actually protects your money.
Start With Financial Readiness, Not Property Hunting
The single biggest beginner mistake is falling in love with a property before confirming what you can actually afford, financed how, without breaking your own financial stability. Before you look at a single listing, work out your realistic budget, your source of funds, and critically how much cash reserve you’ll keep untouched after the purchase for unexpected costs, because there are always unexpected costs.
Understand the Entry Points Available to a Beginner
You don’t need to buy a building to start in real estate. Realistic entry points, roughly in order of capital required, include: buying land in an emerging but verified location, buying a completed residential unit to rent out, joint-venture partnerships with an existing landowner, real estate investment trusts (REITs) for those who want exposure without direct property management, and cooperative or group investment schemes where verified members pool capital for a larger acquisition.
Learn to Verify Before You Learn to Negotiate
Beginners tend to focus energy on getting a good price. That’s the wrong priority order. Before price, verify: is the title genuine and free of encumbrances, is the land free of government acquisition or easement issues, does the seller actually have the right to sell, and does the property match its survey plan on the ground. A “good price” on a property with bad title isn’t a good price it’s a bigger loss waiting to happen.
Build a Small Network Before You Need One
A trustworthy lawyer for title searches, a registered surveyor, an honest agent (they exist more on how to find one below), and ideally a town planner or architect if development is part of your plan. Trying to assemble this team for the first time under the pressure of a closing deadline is how people skip steps.
Your First Deal Should Teach You, Not Just Pay You
Choose a first property that’s manageable enough that mistakes are affordable lessons rather than financial disasters. A modest, well-verified property that performs adequately teaches you far more than an ambitious one that ties up all your capital and patience in year one.
Never let urgency “this offer closes tonight,” “the price goes up tomorrow” override due diligence. Genuine opportunities can survive a week of title and survey verification. Manufactured urgency is one of the most common tools used to sell bad land to first-time buyers.
How to Invest in Real Estate
This is the practical, step-by-step version of everything above, laid out as an actual process you can follow.
Step 1: Define Your Objective Before Your Asset Class
Are you investing for long-term capital appreciation, monthly rental income, a place to eventually build and occupy, or a development project you’ll sell on completion? Each objective points toward a different location, property type, and holding period. Skipping this step is why people end up holding a property that doesn’t match what they actually needed it to do.
Step 2: Set a Realistic Budget Including the Hidden Costs
Purchase price is never the full cost. Legal fees, survey costs, agency commission, governor’s consent or title perfection fees (in Nigeria specifically), and if developing approval and construction costs all sit on top. Budget for the full picture, not just the headline price.
Step 3: Research the Location Independently of the Seller’s Pitch
Talk to people who already live or own property in the area. Check the actual state of roads, drainage, and security independently not through the seller’s photos, which are almost always taken on the one dry, well-lit day the area looks its best.
Step 4: Conduct Due Diligence Before Any Payment
Title search at the relevant land registry, physical verification that the land isn’t under government acquisition, a survey to confirm the plot matches its documented boundaries, and where possible a conversation with neighbouring landowners who often know a plot’s real history better than any document does.
Step 5: Structure the Purchase Correctly
Ensure the sale agreement, receipt, and eventual title documents accurately reflect what you’re buying and from whom. In Nigeria, this typically means working toward a Deed of Assignment and eventually Governor’s Consent or a Certificate of Occupancy, depending on the land’s history a lawyer should guide this, not the seller’s own paperwork.
Step 6: Decide Your Holding Strategy Before You Close
Will you hold this vacant, develop it immediately, or rent it out as-is? Each answer has different tax, maintenance, and security implications from day one of ownership deciding after you’ve already closed the deal usually means you’re improvising instead of executing a plan.
Step 7: Build in an Exit Plan From the Start
Every investment should have a rough exit thesis before you buy it sell after appreciation, refinance and pull equity out, or hold for long-term rental income. An investor without an exit plan tends to hold properties reactively rather than strategically.
Real Estate Investment Strategies
Different strategies suit different capital levels, risk appetites, and time horizons. Here are the core approaches worth understanding, each treated honestly rather than sold to you as universally “the best.”
Buy and Hold
Purchasing property to hold for years, collecting rental income while benefiting from long-term appreciation. This suits investors with patience and stable cash flow needs, but it ties up capital for extended periods and requires ongoing management or a reliable property manager.
Fix and Flip
Buying an underperforming or distressed property, renovating it, and selling for a profit within a relatively short window. This can generate faster returns than buy-and-hold, but it demands accurate renovation cost estimation, reliable contractors, and a realistic read of resale demand flippers who underestimate renovation costs or overestimate resale price are the most common failure pattern in this strategy.
Land Banking
Acquiring undeveloped land in a path-of-growth location and holding it purely for appreciation, with no immediate development or income. This is a patient-capital strategy that depends entirely on correctly reading where infrastructure and demand are actually headed get the location wrong and your capital sits idle for years with no income to show for it.
Development for Sale
Acquiring land, constructing residential or commercial units, and selling them on completion. This generates the highest potential returns of any strategy discussed here, but also carries the highest execution risk construction cost overruns, approval delays, and market shifts between the start and completion of a project can all erode or erase expected profit.
Rental Income Portfolios
Deliberately building a collection of income-generating properties, often across different locations or property types, to diversify rental income and reduce reliance on any single tenant or market. This strategy rewards investors who treat property management as seriously as property acquisition.
Joint Venture Development
Partnering with a landowner who contributes land while an investor or developer contributes capital and construction expertise, sharing the completed units or sale proceeds by an agreed ratio. This is a common and effective way to develop without owning land outright, but it lives or dies on a clear, legally documented agreement covering timelines, cost overruns, and unit allocation before construction starts.
Real Estate Investment Trusts (REITs)
For investors who want real estate exposure without direct property management, REITs allow you to buy shares in a portfolio of income-generating properties, offering liquidity and diversification that direct property ownership cannot match at the cost of the control and direct value-add potential that direct ownership offers.
Match the strategy to your actual temperament, not just your capital. A patient, hands-off investor who buys a fix-and-flip project out of FOMO will make worse decisions under pressure than one who honestly chose buy-and-hold from the start.
Real Estate Development
Development is the process of transforming raw land or an underused property into a finished, higher-value asset through construction, subdivision, or repurposing. It’s a distinct discipline from investing, even though the two are often confused.
The Development Process, Stage by Stage
Development moves through a fairly consistent sequence regardless of scale: site acquisition and due diligence, feasibility study, design and planning approval, financing arrangement, construction, and finally sale, lease, or occupation. Skipping or rushing any single stage especially feasibility and approval is where most development projects run into trouble.
Feasibility Study: The Step Most Developers Skip
A proper feasibility study answers one question honestly: will this project be profitable after every realistic cost is accounted for, including financing cost, approval delays, and a contingency for construction inflation? Many developers skip this in favour of optimism, and the gap between a rushed mental estimate and an honest feasibility study is where most development losses originate.
Land Acquisition for Development
Beyond standard due diligence, developers need to specifically verify zoning classification, permitted density, and any layout or setback restrictions that will determine how much can actually be built on the land a beautiful plot that’s zoned for low-density single-family use cannot support the multi-unit project a developer may have budgeted around.
Financing a Development Project
Development financing typically blends developer equity, construction loans, off-plan sales (pre-selling units before completion), and sometimes joint-venture capital from a landowner or partner. Each financing source has different risk implications off-plan sales, for example, generate early cash flow but create legal and reputational obligations to deliver exactly what was sold, on time.
Managing Construction Risk
Cost overruns, contractor reliability, material price inflation, and approval delays are the four risks that most commonly turn a profitable development plan into a break-even or loss-making one. A realistic contingency budget (typically 10-15% of construction cost) and a genuinely competent project manager or supervising architect are the two most effective defences against this.
Exit Strategy for Developers
Will units be sold individually, sold in bulk to an institutional buyer, or retained for rental income? This decision affects everything from unit design (individual buyers want different things than institutional bulk buyers) to marketing timeline, and should be decided before construction begins, not after completion.
Never start construction on borrowed assumptions about approval timelines. Confirm your actual building plan approval status with the relevant planning authority before committing construction financing to a fixed timeline approval delays are one of the most common and most avoidable causes of development cost overruns.
Real Estate Developers and Development Companies
Understanding what a development company actually does and doesn’t helps you evaluate one properly, whether you’re buying from them, partnering with them, or considering becoming one yourself.
What a Development Company Actually Does
A development company identifies opportunities, acquires or secures land, arranges financing, manages the design and construction process through architects, engineers, and contractors, and ultimately sells or leases the finished product. It is fundamentally a project management and risk-bearing entity, not a construction company many developers subcontract actual construction entirely.
How to Evaluate a Developer Before Buying From Them
Check their track record on previously completed projects, not just their marketing renders visit a completed project if at all possible. Verify their land title and approval status for the specific project you’re considering, independently of their claims. Ask specifically about their history of delivering on promised timelines, since construction delays are common across the industry and a developer’s honesty about past delays tells you more than a clean sales pitch does.
Structuring a Small Development Business
If you’re building a development business rather than doing one-off projects, the core decisions are: what property type and price segment you’ll specialize in, how you’ll finance land acquisition and construction (your own capital, joint ventures, or institutional financing), and how you’ll build a repeatable, reliable team of contractors and professionals rather than starting from scratch on every project.
The Reputation Economy in Development
In a market where formal legal enforcement of contracts can be slow, a development company’s reputation for delivering as promised, on the timeline promised is arguably its most valuable asset, more valuable in the medium term than any single project’s profit margin. Developers who cut corners on one project to maximize short-term profit often find that reputation damage costs them far more in future sales than the corner-cutting saved.
Real Estate Market and Market Trends
Understanding market dynamics helps you time entries, avoid overpaying, and recognize genuine opportunity versus manufactured hype.
What Actually Moves a Real Estate Market
Population growth and urbanization (more people needing housing in a given area), infrastructure investment (roads, rail, power that make a previously inconvenient area viable), interest rates and financing availability, income growth or decline in the local economy, and government policy (housing schemes, land use reforms, tax changes) are the fundamental forces everything else is noise layered on top of these.
Reading Nigeria’s Current Market Reality
Nigeria’s real estate sector has grown into one of the country’s largest economic sectors, with residential property continuing to dominate overall activity, while commercial and industrial segments expand at a notable pace. Urbanization and population growth remain the primary structural drivers of demand, with over 60% of Nigerians now living in urban areas and continued migration toward major cities. At the same time, the market carries a well-documented housing deficit running into tens of millions of units, alongside limited mortgage access and construction costs that remain sensitive to inflation and currency movement.
Where Growth Is Concentrating
Growth in 2026 is increasingly following infrastructure corridors rather than established prime districts alone emerging suburban and peri-urban belts along major road and rail expansion projects are seeing faster relative appreciation than already-mature, fully priced-in prime areas, as rental demand across most major cities continues to outpace new supply.
The Difference Between a Hot Market and a Sustainable One
A hot market is driven by speculation and rapid price movement with limited underlying end-user demand. A sustainable market is driven by genuine occupancy people actually living in, working from, or operating businesses out of the properties being bought and sold. The current shift many analysts describe, away from speculative cycles and toward genuine end-user demand, is a healthier signal for long-term investors than a purely speculative boom, even if it produces less dramatic short-term price movement.
Reading Market Cycles
Real estate moves through recognizable phases recovery, expansion, oversupply, and correction though the exact timing and severity differs by market and property type. Understanding which phase your target market is currently in helps you calibrate whether you’re buying into genuine growth or arriving late to a cycle that’s already peaking.
Don’t just track prices track vacancy rates and time-on-market for comparable properties in your target area. Rising prices alongside rising vacancy and slower sales is a warning sign of speculative excess, not genuine demand-driven growth.
Real Estate Investment Opportunities
Where the actual opportunities sit right now, read honestly rather than as a sales pitch.
Mid-Market and Affordable Housing
In several major Nigerian cities, high-end residential supply has notably outpaced effective demand, leaving luxury units vacant, while the mid-market and affordable housing segments remain structurally undersupplied relative to genuine demand. This mismatch is one of the clearer, less-hyped opportunities in the current market for investors willing to build or buy at a more accessible price point.
Infrastructure-Linked Corridors
Areas benefiting from active road, rail, or power infrastructure expansion tend to see disproportionate appreciation as they transition from inconvenient to accessible but this requires genuine research into confirmed, funded infrastructure projects rather than speculative rumours repeated by land sellers to justify a price increase.
Rental Property in Tight Rental Markets
With rental demand structurally outpacing supply in most major Nigerian cities and rents rising well above general inflation and wage growth in recent years, well-located rental property remains one of the more dependable income-generating opportunities, provided the underlying purchase price and rental yield genuinely make sense together.
Logistics, Warehousing, and Industrial Real Estate
Growing e-commerce and distribution activity is increasing demand for logistics and warehousing space in peri-urban corridors near major cities a segment with less competition from individual investors than residential property, but requiring different due diligence around access roads, power reliability, and zoning.
Student and Institutional Accommodation
Purpose-built accommodation near major universities and institutions represents a specific, often underserved niche with predictable, recurring demand tied to academic calendars rather than general market sentiment.
Diaspora-Driven Development Demand
Nigerians abroad continue to represent a significant and consistent source of capital for residential development back home, creating opportunities for developers and agents who can offer genuinely trustworthy, well-documented transactions to a buyer who cannot personally inspect the property before purchase trust and documentation quality are the actual product being sold to this segment, more than any specific location.
Residential, Commercial and Industrial Real Estate
These three categories behave differently enough that treating them as interchangeable is a common and costly beginner mistake.
Residential Real Estate
Covers single-family homes, duplexes, apartments, and multi-family housing intended for people to live in. It currently dominates the Nigerian market by a wide margin, driven by direct, universal human need rather than economic cycles alone everyone needs somewhere to live regardless of broader economic conditions, which gives residential demand a baseline resilience that commercial and industrial segments don’t always share.
Commercial Real Estate
Includes office space, retail, hospitality, and mixed-use developments intended for business activity. Commercial property tends to be more sensitive to broader economic conditions than residential a downturn reduces business expansion and retail spending faster than it reduces people’s basic need for housing but well-located commercial property can command higher yields and longer lease terms than residential.
Industrial Real Estate
Covers warehouses, logistics facilities, manufacturing space, and distribution centres. This segment is growing in Nigeria alongside e-commerce and manufacturing expansion, and it rewards investors who understand specific requirements access road quality for heavy vehicles, power reliability, and proximity to ports or major transport routes that differ significantly from residential due diligence.
Choosing Between the Three as an Investor
The right category depends on your capital, risk tolerance, and management capacity. Residential offers the broadest demand base and lowest entry barrier for most investors. Commercial offers potentially higher yields but more cyclical risk and typically requires larger capital. Industrial offers a growing, less-crowded opportunity but demands more specialized due diligence than most individual investors are equipped to do without professional guidance.
Real Estate Property
“Property” in real estate isn’t just the physical structure it’s a bundle of legal rights, and understanding that bundle protects you far more than understanding square footage does.
What You’re Actually Buying When You Buy Property
You’re acquiring rights to occupy, to use, to lease, to sell, to build on (subject to planning permission), and to exclude others. Different title types (freehold, leasehold, customary right of occupancy) grant different bundles of these rights, and confusing one for another is a common and expensive misunderstanding.
Types of Property Interests
Freehold ownership grants the fullest bundle of rights, typically indefinite. Leasehold grants rights for a defined period, after which they may need renewal or revert to the landowner. In Nigeria specifically, land is technically vested in the state under the Land Use Act, and what individuals hold is typically a right of occupancy understanding this distinction matters enormously for anyone buying land expecting freehold-equivalent rights.
Physical Property Characteristics That Actually Matter
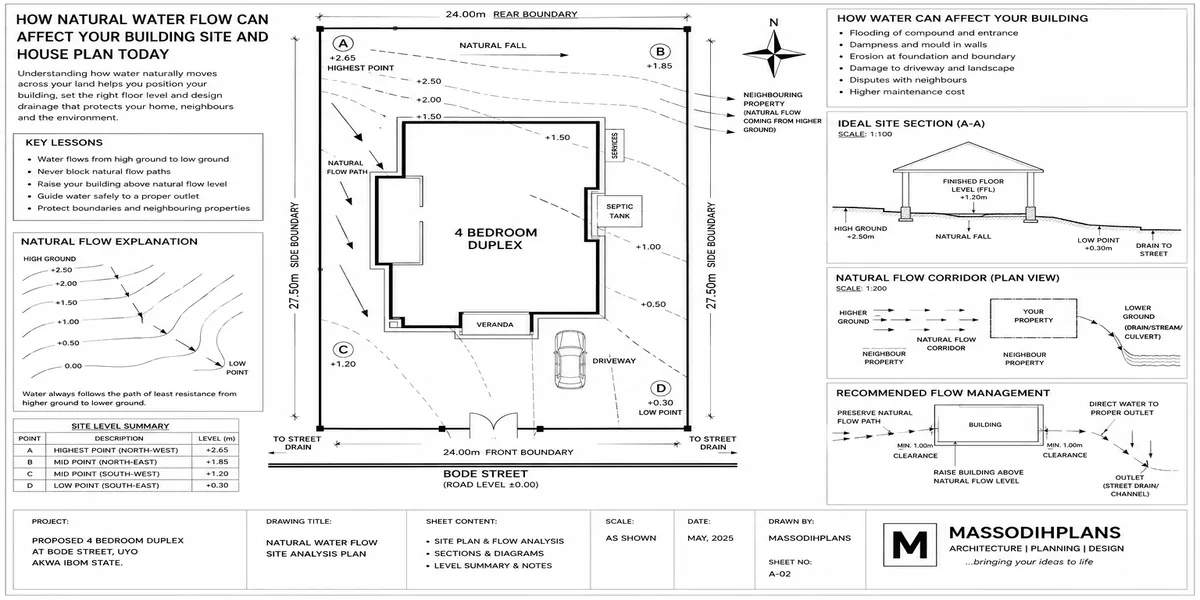
Beyond the legal bundle, physical characteristics soil condition, drainage, topography, access, and orientation determine what can actually be built and how much it will cost to build it. A legally clean title on a plot with poor soil or drainage problems is still a property with real, budgetable development challenges.
Encumbrances and How They Affect Property Value
Mortgages, liens, easements, and unresolved family or community claims on land can all reduce a property’s value or make it entirely unsellable until resolved. A thorough title search exists specifically to surface these before you commit money, not after.
Real Estate Business
Building a business around real estate rather than making individual investment decisions requires thinking in systems, not transactions.
Different Business Models Within Real Estate
You can build a business as an investor (acquiring and holding property for your own portfolio), a developer (building and selling), an agent or broker (facilitating transactions for commission), a property manager (managing properties for other owners), or some combination of these. Each has a different capital requirement, skill set, and risk profile.
Why Most Real Estate Businesses Fail in the First Few Years
Undercapitalization (not having enough reserve to survive slow periods), poor systems (no consistent process for due diligence, client management, or financial tracking), and overreliance on a single relationship or deal type (one big client, one land source) are the three most common failure patterns, far more often than a genuinely bad initial idea.
Building Systems That Scale
A real estate business that depends entirely on the founder’s personal relationships and memory doesn’t scale it caps out at whatever one person can personally manage. Documented processes for due diligence, client onboarding, and financial tracking are what allow a real estate business to grow beyond its founder’s personal capacity.
Diversifying Revenue Within a Real Estate Business
Many successful real estate businesses combine revenue streams brokerage commission alongside property management fees, or development profit alongside consulting fees for smaller clients rather than depending on one transaction type, which smooths out the inevitable slow periods any single revenue stream experiences.
If you’re building a real estate business, track your numbers as seriously as any other business cost per lead, conversion rate, average deal size, and time-to-close. Real estate businesses that treat themselves as “just relationships” rather than measurable operations rarely scale past their founder’s personal network.
Real Estate Agents, Agencies, Brokers and Brokerage
This is one of the most misunderstood corners of the industry, partly because entry barriers are genuinely low and partly because bad actors have damaged trust in the profession broadly.
What an Agent Actually Does (and Doesn’t)
A competent agent facilitates transactions connecting buyers and sellers, arranging viewings, negotiating terms, and guiding paperwork. What a good agent does not do is replace independent legal due diligence even an honest agent’s job is to close the transaction, not to protect your specific legal interests the way your own lawyer does.
The Difference Between an Agent, a Broker, and an Agency
An agent typically represents a specific transaction or client relationship. A broker often operates with a wider license or oversight responsibility, sometimes managing a team of agents. An agency is the business entity that houses agents and brokers, providing brand, systems, and sometimes verified listing inventory. In markets with less formal regulation, these distinctions blur significantly, which is exactly why verifying an individual’s track record matters more than their title.
How to Identify a Trustworthy Agent
Ask for verifiable past transactions, not just testimonials. A trustworthy agent willingly connects you with previous clients and doesn’t discourage independent legal due diligence in fact, a good agent actively supports it, because it protects the transaction from collapsing later over a title problem. An agent who pressures you to skip verification steps is showing you exactly who they are.
Building a Brokerage as a Business
For those on the agent/brokerage side of the industry, the business fundamentals are lead generation, deal conversion, and most importantly for long-term survival reputation management in a market where word-of-mouth trust travels faster than any advertising. A brokerage’s real asset is the accumulated trust of past clients, not its listing inventory alone.
Real Estate Appraisal and Valuation
Valuation is where emotion and reality most often collide in real estate, and understanding the actual methods protects you from both underpaying sellers unfairly and overpaying as a buyer.
Why Valuation Matters Beyond Just “What’s a Fair Price”
Accurate valuation matters for purchase decisions, but also for financing (lenders base loan amounts on appraised value, not asking price), insurance, taxation, and eventual resale planning. A property bought without any real valuation logic is a property whose owner genuinely doesn’t know what they hold.
The Three Core Valuation Approaches
The sales comparison approach values a property based on recent comparable sales in the same area the most common approach for residential property, and only as reliable as the quality and true comparability of the sales data used. The income approach values a property based on the income it generates or could generate, dividing net income by a market capitalization rate standard for rental and commercial property. The cost approach values a property based on what it would cost to replace the land and structure at current prices, minus depreciation most useful for unique properties with limited comparable sales.
What a Professional Valuer Actually Assesses
Beyond comparable prices, a professional appraisal considers location quality, physical condition, legal status of title, current and permitted use, income potential, and broader market conditions a genuinely qualified valuer’s report carries far more weight (and legal defensibility, where needed) than an agent’s informal price opinion.
Common Valuation Mistakes
Relying entirely on asking prices from similar listings (which reflect what sellers hope for, not what buyers actually pay) rather than closed sale prices; ignoring the specific condition and legal status of the property being valued; and failing to adjust comparable sales for genuine differences in size, location, and condition are the most frequent errors, made by professionals and amateurs alike.
Never rely solely on the seller’s or agent’s stated valuation, and don’t rely solely on a single online estimate either. Where the transaction size justifies it, commission an independent valuation from a registered estate surveyor and valuer the cost is small relative to the protection it provides against a significantly mispriced transaction.
Property Valuation
Building directly on the above, here’s how to think about valuation from the perspective of someone actually about to buy, sell, or develop not just the theory behind it.
Valuation for Buyers
As a buyer, valuation protects you from overpaying based on emotional attachment or a seller’s optimistic pricing. Get genuinely comparable recent sales data not listing prices for similar properties in the immediate area, and be honest with yourself about whether a property’s unique features actually justify a premium over those comparables, or whether you’re rationalizing a price you already want to pay.
Valuation for Sellers
As a seller, understanding realistic valuation prevents both underpricing (leaving money on the table) and overpricing (a property that sits unsold for months, eventually forcing a price cut that signals desperation to buyers). A property priced accurately from the start typically sells faster and closer to its true value than one that starts high and gets progressively discounted.
Valuation for Developers
For developers, valuation isn’t just about the finished product it’s about working backward from realistic sale or rental value to determine what land acquisition and construction costs can actually be justified. A development budgeted from cost forward, without checking whether the market will actually support that price on completion, is a common and expensive planning failure.
Factors That Move Valuation Beyond the Property Itself
Neighbourhood trajectory (improving or declining), proximity to infrastructure and amenities, security perception, and broader market sentiment all affect valuation independently of the physical property’s own condition which is why the same house can be worth meaningfully different amounts depending purely on which street it sits on.
Property Investment and Development
Bringing investment and development together, here’s how the two disciplines actually interact in a single project’s lifecycle.
The Investor’s Perspective on Development Projects
An investor considering a development project (rather than a completed property) needs to evaluate the developer’s track record, the realism of the project’s timeline and costing, and the strength of the legal documentation covering their specific stake or unit off-plan investment carries real delivery risk that a completed-property purchase doesn’t.
The Developer’s Perspective on Investment Returns
A developer needs to think like an investor when planning a project what return does the finished product need to generate to justify the land, construction, financing, and time invested, and does realistic market demand actually support that return, or is the projection built on hopeful assumptions?
Where Investment and Development Risk Genuinely Differ
Pure investment in a completed property carries market risk (will it appreciate or generate expected income) but limited execution risk. Development carries both market risk and substantial execution risk (construction cost overruns, approval delays, contractor reliability) layered on top which is why development, done well, typically demands and deserves a higher expected return than passive investment in a completed property.
Blending the Two as a Strategy
Many successful property portfolios deliberately blend both holding some completed, income-generating properties for stability while allocating a portion of capital to development projects for higher potential returns. This balances the predictability of investment income against the higher-risk, higher-reward nature of development.
Property Investment Strategies
Distinct from the broader real estate investment strategies covered earlier, here are approaches specific to how you structure and manage a property investment over time.
Diversification Across Location and Property Type
Concentrating all capital in a single location or property type exposes an investor to risks specific to that market — a single infrastructure delay, a local oversupply, or a policy change can affect an entire concentrated portfolio simultaneously. Spreading investment across a few genuinely different locations or property types reduces this concentration risk meaningfully.
Leverage and Financing Strategy
Using financing to control more property than your cash alone would allow can amplify returns, but it also amplifies risk a leveraged property that loses value or underperforms in rental income can create genuine financial strain if the financing terms weren’t realistically stress-tested against a slower-than-expected scenario.
Value-Add Strategy
Actively improving a property’s income or value through renovation, better management, subdividing, or repositioning its use rather than passively waiting for market appreciation. This strategy demands more hands-on involvement but reduces reliance on broader market movement alone to generate returns.
Income Reinvestment Strategy
Systematically reinvesting rental income or sale proceeds into acquiring additional properties, compounding a portfolio’s growth over time rather than extracting all income for personal use. This is a patient, deliberate strategy that rewards consistency over any single dramatic deal.
Timing and Market Cycle Awareness
Buying during market downturns or periods of temporary oversupply, when motivated sellers are more common and prices are softer, generally produces better long-term returns than buying during a visible boom when competition and prices are both elevated though this requires the patience and liquidity to wait for those windows rather than needing to deploy capital immediately.
Rental Property and Rental Properties
Rental income is often the entry point for new investors, and it deserves treatment as a genuine operating responsibility, not a passive afterthought.
Evaluating a Property for Rental Potential
Beyond purchase price, calculate realistic achievable rent for the specific location and property type, then work out gross rental yield (annual rent divided by purchase price) and, more importantly, net yield after realistic expenses maintenance, vacancy periods, management costs, and any applicable levies or taxes. A property with an impressive gross yield can be mediocre once realistic net costs are factored in.
Tenant Selection and Management
Thorough tenant screening verifiable employment or income, references from previous landlords where possible, and a clearly documented tenancy agreement prevents the majority of rental headaches before they start. Reactive property management (only engaging when there’s a problem) tends to produce worse tenant relationships and slower issue resolution than proactive, regular engagement.
Maintenance as a Value-Preservation Strategy, Not a Cost Center
Deferred maintenance doesn’t save money it defers a larger cost while allowing the property to depreciate faster and potentially damaging tenant relationships in the meantime. Budgeting a consistent portion of rental income specifically for maintenance protects both the property’s value and its income-generating reliability.
Vacancy Management
Realistic rental income projections must account for vacancy periods between tenants a property that sits empty for even one or two months a year has a materially different actual yield than the “fully occupied” projection most sellers and agents quote. Reducing vacancy through competitive pricing, good property condition, and responsive management is one of the highest-leverage things a rental property owner can control directly.
Self-Management vs. Professional Property Management
Self-managing saves the management fee but demands genuine time and availability, especially for issue response and tenant communication. Professional management costs a percentage of rental income but frees the owner’s time and, with a genuinely competent manager, often improves tenant retention and issue resolution the right choice depends honestly on the owner’s available time, number of properties, and geographic proximity to them.
Calculate your rental property’s net yield using a realistic vacancy assumption even a well-managed property, budget for at least one month of vacancy per year in your projections. An investor who only ever calculates yield assuming zero vacancy is calculating a number that doesn’t actually exist.
The Layers Most Real Estate Content Leaves Out
A few things worth adding that rarely appear in the usual real estate investing content, because they come from the planning and design side of the industry rather than the purely financial side.
Zoning and Land Use as an Investment Variable
Most real estate content treats “location” as a single variable good or bad. In reality, a plot’s zoning classification and permitted density directly determine what can legally be built and, therefore, what the land is actually worth to a developer versus what it might casually appear to be worth based on nearby comparable sales. Two plots on the same street can carry meaningfully different investment value purely based on their zoning status.
Infrastructure Capacity as a Hidden Risk
A location can have excellent road access today and still be a poor long-term investment if the surrounding drainage, power, and water infrastructure weren’t planned for the density that’s actually being built. Investors who check current road access but never ask about underlying infrastructure capacity are missing a risk that often only becomes visible years after purchase, once an area is fully built out and its infrastructure limits become obvious.
The Planning Approval Timeline as a Financial Variable
Most investment calculations treat approval as a formality with a predictable timeline. In practice, approval delays are one of the most common and financially significant risks in development, and they’re rarely modeled honestly in feasibility studies building a realistic approval timeline buffer into any development financial model is a discipline that separates experienced developers from optimistic first-timers.
Reading a Site Beyond Its Sale Listing
A genuinely useful skill most investment guides never teach: reading a plot’s actual physical reality soil condition, drainage pattern, existing easements, and relationship to neighbouring development independently of how it’s marketed. The gap between a plot’s marketing description and its physical and legal reality is where most bad investment outcomes originate, and it’s a gap that a site visit with a qualified professional closes far more reliably than any amount of document review alone.
Frequently Asked Questions
How much money do I need to start investing in real estate?
It depends entirely on your entry point land in an emerging area, a completed rental unit, or a joint-venture partnership all require very different capital levels. The more important starting question isn’t “how much do I need” but “what can I afford to lose or have tied up for years without financial strain,” since real estate is illiquid by nature.
Is it better to invest in land or a completed building?
Land typically requires less capital and can appreciate significantly if the location is correctly read, but generates no income while held. A completed building costs more but can generate rental income immediately. The right choice depends on your objective pure appreciation versus ongoing cash flow.
What is the biggest mistake new real estate investors make?
Skipping thorough due diligence title verification, survey confirmation, and zoning checks under pressure of manufactured urgency from a seller or agent. Almost every serious real estate loss I’ve seen traces back to a due diligence step that was skipped or rushed.
How do I know if a rental property will actually be profitable?
Calculate net yield, not just gross yield factor in realistic vacancy periods, maintenance costs, management fees, and any applicable levies, not just the headline rent divided by purchase price.
Do I need a real estate agent, or can I buy directly from a developer or landowner?
You can buy directly, but a trustworthy agent can add value through market knowledge and negotiation. Either way, independent legal due diligence should never be skipped, regardless of who facilitates the transaction.
What’s the difference between a real estate investor and a real estate developer?
An investor primarily acquires and holds property (existing or land) for income or appreciation. A developer actively transforms property through construction, subdivision, or repurposing bearing significantly more execution risk in exchange for potentially higher returns.
Conclusion
Real estate rewards the people who treat it as a discipline, not a gamble dressed up in property photos. Every strategy in this guide investing, developing, valuing, renting, building a business around it comes back to the same underlying habit: verify before you commit, understand what you’re actually buying, and never let urgency replace due diligence. That habit alone will keep you out of more trouble than any market timing skill or negotiation tactic ever will.
If land use, zoning, or development feasibility is part of what you’re weighing right now, our Services page outlines how we support clients through the planning and design side of a property project. Browse our Plans Library if you’re at the stage of turning land into a buildable home, or visit Plan School to understand the planning and approval process before you commit capital to a development. You can also explore more building and property guides on our Homepage. See also Approval process in lagos
Related Guides
- How Much Does It Cost to Build a House and Develop a Property?
- Can I Change the Use of My Land? Planning Rules and Approval Process
- What Is the Zoning of My Property? How to Check Zoning Before Building
- What Can I Build On My Land? How to Find Out What You Can Build There?
- Property for Sale in Nigeria: The Buyer’s Guide Nobody Publishes Today
- Estate Layout Design Services for Property Developers in Nigeria
- How Much Does It Cost to Develop an Estate in Nigeria? A Town Planner’s Honest Breakdown
- Property for Sale in Nigeria: The Buyer’s Guide Nobody Publishes Today
- Building Permit Documents: Complete Checklist of Requirements for Building Approval
- I Need a Real Estate Agent to Help Me Buy a Property in Nigeria Safely
- Real Estate Development & Site Planning: Guide to Planning, Construction, Infrastructure and Stormwater Management
- How to Invest in Nigerian Real Estate from Abroad: Complete Guide for Diaspora Investors
- Landscape Design and Planning for Residential, Estate and Commercial Plans
Author
Massodih Okon is a Nigerian built-environment professional with academic and professional experience in urban and regional planning, geography, architectural design, Landscape Design, GIS and land development.
He holds a Master’s degree in Urban and Regional Planning from the University of Uyo and a first degree in Geography and Regional Planning.
Through MassodihPlans, he publishes practical guides on Nigerian house plans, building design, physical planning, site planning, development approval and residential construction. Read the full author profile →